- ZPenTeam zpenteam@uk.zurich.com
- ZCB Zcashbuilder@broadstone.co.uk
- Pensioners zurichteam@broadstone.co.uk
Your Pension - Your Future

Investments
The range of investments offered by LifeSight is managed by WTW, and Legal & General Investment Management is the investment platform provider.
You will get access to LifeSight’s wide range of investment options - which means more flexibility to choose investments that match your plans and preferred level of risk.
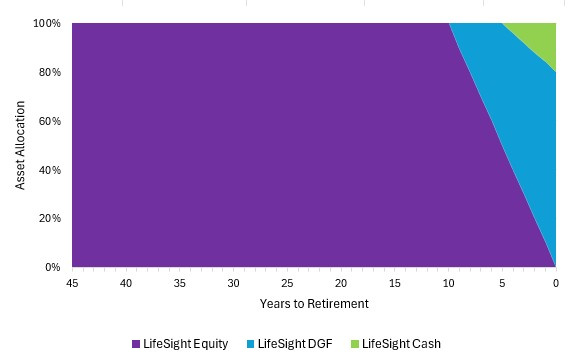
This is where your LifeSight Account savings will be automatically invested if you don’t make an investment choice. The default option is a ready-made investment strategy designed for members who want to take a flexible income from their pension (income drawdown). It automatically switches where a member’s savings are invested, based on how far the member is from their selected Target Retirement Age (TRA).
This strategy aims for investment growth in the earlier years (when you’re saving for retirement and have time to weather any ups and downs in the investment markets). As you get closer to your TRA, the strategy moves your savings to more stable investments.
These are alternative ready-made strategies. Like the default option, these strategies automatically switch where a member’s savings are invested, based on how far the member is from their selected Target Retirement Age (TRA).
You will be able to choose from different lifecycle strategies, depending on:
- how much risk you would like to take (low, medium or high)
- how you want to take your pension (as drawdown, annuity or cash
If you prefer to have more control over how your savings are invested, you will have access to LifeSight’s range of Freechoice funds.
Choosing how to invest your savings is an important decision – the value of your pension will depend partly on how well your investments perform over time.
If you choose to invest in one or more of the Freechoice funds, there are many things you should consider when making an investment choice, including:
- how far you are from reaching your Target Retirement Age
- what level of risk you are comfortable taking with investment performance
- how you feel about responsible investment
- how you plan to take your pension
You can find out more about the investment options you would get access to from LifeSight here:
Default options
The default option is where your savings are automatically invested if you do not make a choice about your investments. As a result of the move to LifeSight you will have a new default option.
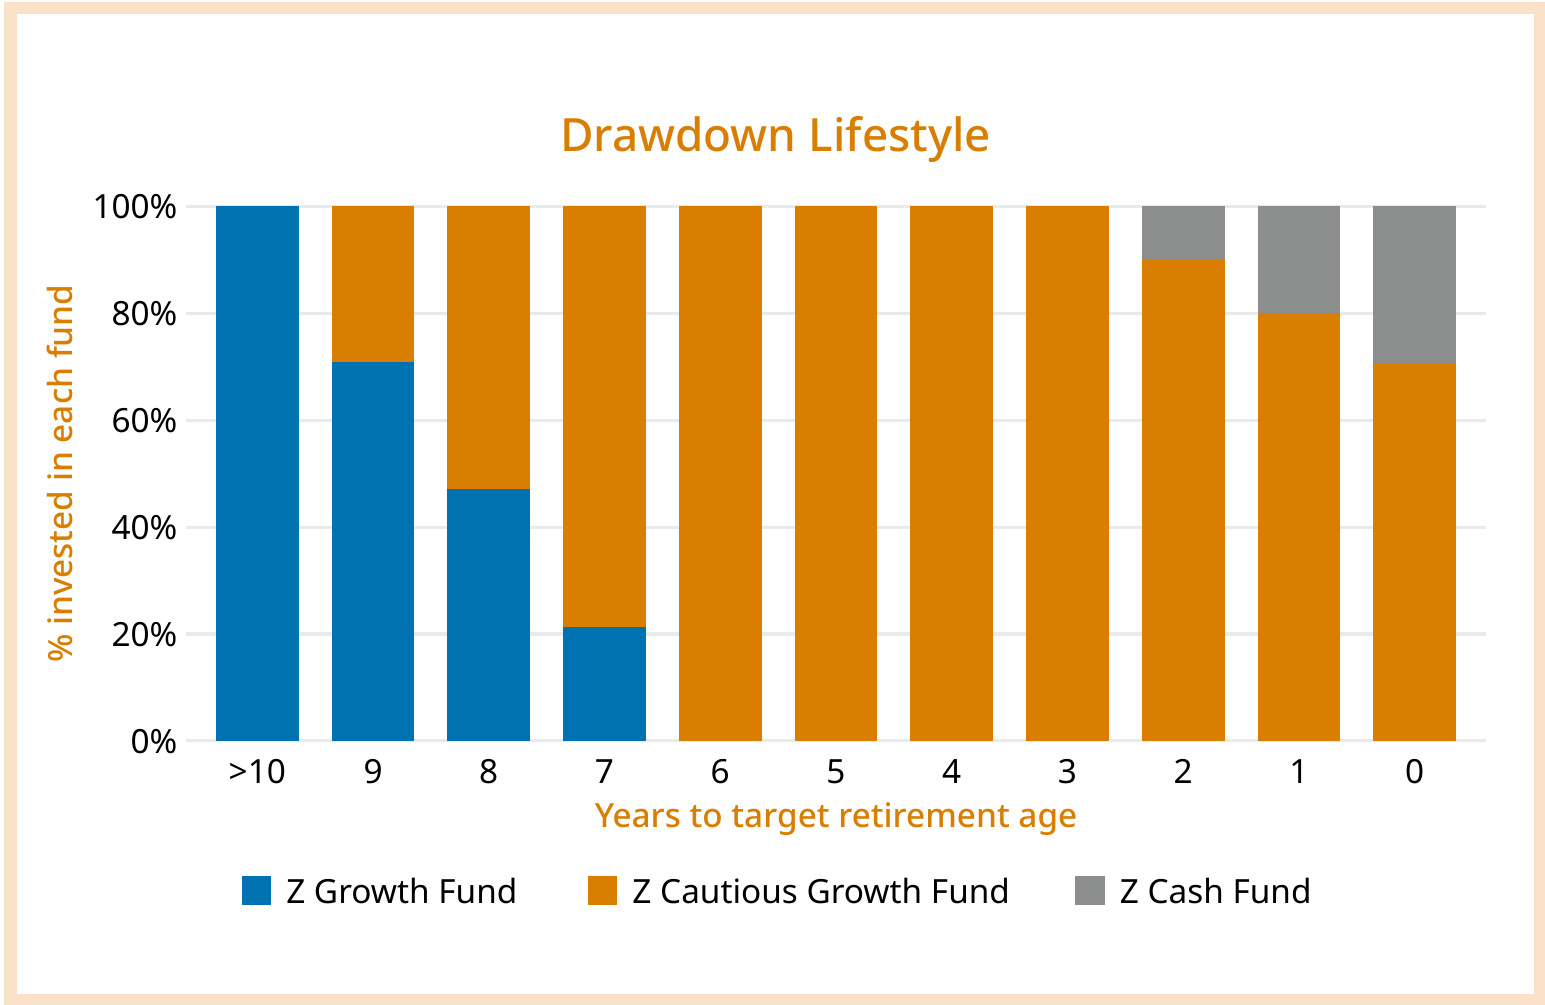
The table below shows how the new default compares to your current default option (the ZPen Drawdown Lifestyle for most members).
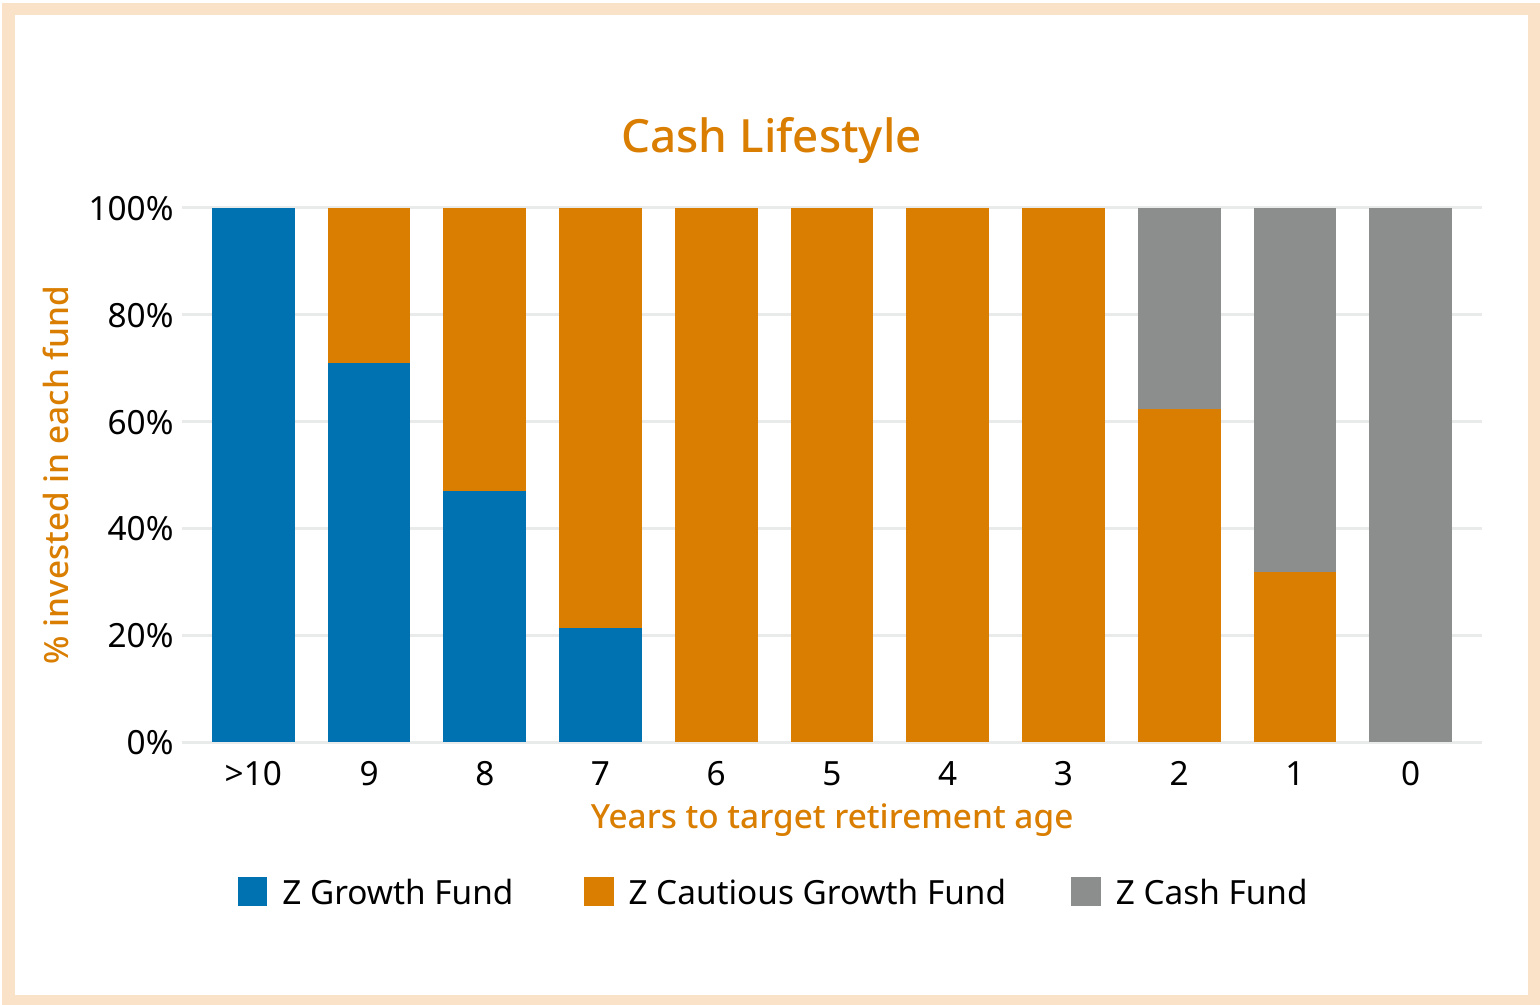
If you also have a Final Salary pension, you have a different default option – the ZPen Cash Lifestyle.
ZCashBuilder default option | LifeSight default strategy | |
ZCashBuilder only | ZCashBuilder Drawdown Lifestyle
This is where your ZCashBuilder savings are automatically invested now if you do not make an investment choice. Your investments start moving to lower-risk funds (corporate bonds and cash) when you are 10 years away from your Target Retirement Age. Depending on how far you are from retirement, the total investment charges range from 0.28% to 0.35% for the ZCashBuilder Drawdown Lifestyle. This investment option would not be available after the move to LifeSight. | Drawdown Lifecycle
This is similar to the current default investment strategy so the move should not significantly change your asset allocation or the investment risk you are exposed to. You would keep the same Target Retirement Age that you have in ZCashBuilder, and if your savings were invested in the proposed new default (or another lifecycle), your investments would switch based on the same Target Retirement Age you have today. Just as you can today, you would be able to change your Target Retirement Age if it did not match your retirement plans. Depending on how far you are from retirement, the total investment charges would range from 0.13% to 0.14% for the Zurich Drawdown Lifecycle. These charges would be significantly lower than what you pay today. If you do not want to be in this investment strategy you can choose from nine other LifeSight strategies, or self-select funds. |
If you have final salary benefits and are more than five years from your target retirement age in February 2027 | ZCashBuilder Cash Lifestyle
This is where your ZCashBuilder savings are automatically invested now if you do not make an investment choice. Your investments start moving to lower-risk funds (corporate bonds and cash) when you are 10 years away from your Target Retirement Age. Depending on how far you are from retirement, the total investment charges range from 0.06% to 0.35% for the ZCashBuilder Drawdown Lifestyle. This investment option would not be available after the move to LifeSight.
| Drawdown lifecycle
The key differences between these two strategies is in the three years before retirement, so the move should not significantly change your asset allocation or the investment risk you are exposed to. You would keep the same Target Retirement Age that you have in ZCashBuilder, and if your savings were invested in the proposed new default (or another lifecycle), your investments would switch based on the same Target Retirement Age you have today. Just as you can today, you would be able to change your Target Retirement Age if it did not match your retirement plans. Depending on how far you are from retirement, the total investment charges would range from 0.10% to 0.15% for the Zurich Cash Lifecycle. These charges would be significantly lower than what you pay today. If you do not want to be in this investment strategy you can choose from nine other LifeSight strategies, or self-select funds. |
If you have final salary benefits and are five years or less from your target retirement age in February 2027 | ZPen Cash Lifestyle
This is where your ZCashBuilder savings are automatically invested now if you do not make an investment choice. Your investments start moving to lower-risk funds (corporate bonds and cash) when you are 10 years away from your Target Retirement Age. Depending on how far you are from retirement, the total investment charges range from 0.06% to 0.35% for the ZCashBuilder Drawdown Lifestyle. This investment option would not be available after the move to LifeSight. | Cash lifecycle 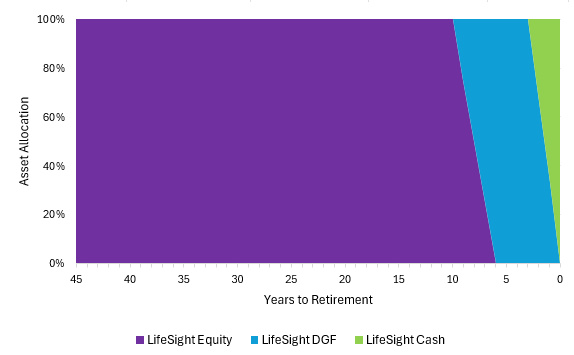 This is similar to the current default investment strategy so the move should not significantly change your asset allocation or the investment risk you are exposed to in the remaining years to your target retirement age. You would keep the same Target Retirement Age that you have in ZCashBuilder, and if your savings were invested in the proposed new default (or another lifecycle), your investments would switch based on the same Target Retirement Age you have today. Just as you can today, you would be able to change your Target Retirement Age if it did not match your retirement plans. Depending on how far you are from retirement, the total investment charges would range from 0.10% to 0.15% for the Zurich Cash Lifecycle. These charges would be significantly lower than what you pay today. If you do not want to be in this investment strategy you can choose from nine other LifeSight strategies and the Zurich Drawdown Lifecycle. If you opt out of this lifecycle you will not be able to move back in. |